News
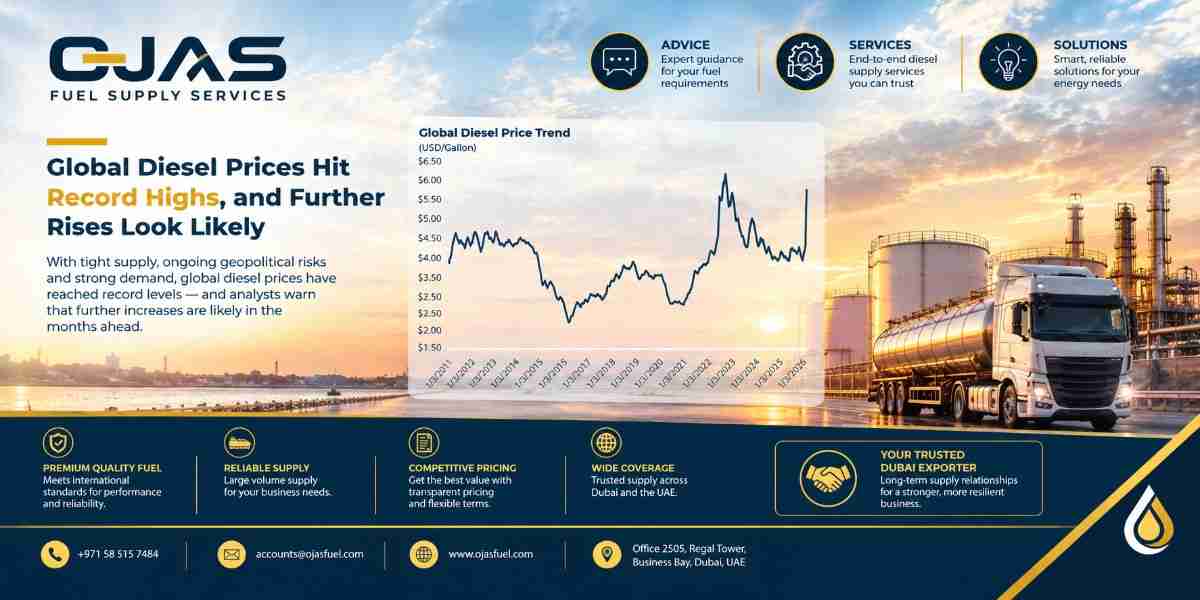
Global Diesel Prices Hit Record Highs, and Further Rises Look Likely
Diesel has become one of 2026’s most disruptive commodities.
Prices in Europe, the United States, and Asia have all pushed past previous records, driven by wars in Iran and Ukraine that have crippled exports from three of the world’s biggest diesel suppliers: Russia, Saudi Arabia, and the United Arab Emirates.
For buyers, traders, and fuel-dependent industries across the UAE and globally, this is not a short-term spike. It is a structural supply shock, and analysts warn the tightness could persist well into 2027.
Why Diesel Is Breaking Records
The core problem is simple: refining capacity is stretched thin everywhere at once.
The International Energy Agency said in its September 21 newsletter that “many refineries around the world are already stretched to capacity,” leaving “few available options to prevent a further tightening of supplies and higher prices in the coming months.”
Three forces are compounding the squeeze. First, Middle East diesel exports halved between March and August compared with a year earlier, averaging just 800,000 barrels per day, according to shipping data from Kpler. The region supplied nearly 41% of Europe’s diesel imports in 2025, so this drop hits hard.
Second, Russia banned diesel exports in July after Ukrainian drone strikes damaged its refineries, and Moscow has since extended that ban through the end of October. Russia is the world’s second-largest diesel exporter after the United States, and countries like Turkey and Brazil that relied on Russian barrels have had to scramble for alternatives.
Third, supply disruptions have spread to the Red Sea, the route Saudi Arabia uses to load most of its diesel exports. Kpler analyst George Shaw noted that any further disruption to Red Sea flows risks tightening an already stretched global diesel market.
Record Prices Across Three Continents
In the United States, retail diesel crossed USD 6 a gallon for the first time on record earlier in September, then kept climbing to top USD 6.50 a gallon by September 21, according to AAA figures cited by Bloomberg.
That marks roughly a 60% jump since the U.S. and Israel struck Iran in late February. The U.S. diesel crack spread, a key measure of refining profitability, hit a record USD 118.62 a barrel on September 14.
In Europe, diesel futures closed at an all-time high last week, having more than doubled since the start of 2026. Physical cargo prices tell the same story: the 10ppm CIF Northwest Europe benchmark hit USD 1,642.25 per metric ton on September 15, its highest level since S&P Global Platts began the assessment.
The EU’s weighted average pump price reached EUR 2.26 per liter on September 17, a 38% increase since February 27. In the UK, average diesel prices have climbed 38% since the crisis began and are expected to reach GBP 2 a litre within days.
In Asia, diesel swaps, the regional benchmark, have eased from a March peak above USD 200 a barrel to around USD 180 a barrel on September 18, still roughly double pre-war levels.
China’s diesel exports fell 26% in April-June due to government export limits but rebounded to a near two-and-a-half-year high of 320,000 barrels per day in August, which has pulled down its own domestic stocks in the process.
Inventories Are Draining Fast
Behind the price rally sits a deepening inventory crisis. U.S. total diesel stocks fell to 107.9 million barrels by September 11, the lowest for this time of year since records began in 1982, according to the U.S. Energy Information Administration.
The EIA expects U.S. distillate inventories to stay below 100 million barrels through September and remain under the five-year low for the rest of 2026 and most of 2027.
Europe is not much better off. Stocks at the Amsterdam-Rotterdam-Antwerp trading hub sat 16% below their five-year average in July and hit their lowest level for this time of year on September 10. Singapore’s distillate inventories are running below the 2025 average as well.
A telling signal comes from the storage market itself.
North American diesel storage capacity available for lease climbed to a four-year high of 13 million barrels for October, up from 11 million barrels in June, according to storage broker The Tank Tiger.
That is unusual, because it means traders are declining to renew leases simply because there is too little diesel left to store.
What Happens Next
Most industry voices expect the tightness to persist through winter rather than ease quickly.
StoneX energy strategist Alex Hodes said U.S. diesel prices could rise further as East Coast buyers stock up ahead of the heating season, adding that current fundamentals point to higher prices staying here for a while.
There are a few pressure valves. Record refining margins are incentivizing more production, and China’s rising exports could offer some relief, according to energy economist Philip Verleger. U.S. refinery utilization also reached 98% in the week ending August 28, the highest since 2018.
But the risk sits firmly to the upside: any escalation in the Iran or Russia-Ukraine conflicts, or a major refinery outage, could trigger a fresh spike.
The View From the UAE
The UAE sits on both sides of this story, as an exporter losing ground and as a consumer feeling the pinch.
The UAE’s monthly fuel pricing mechanism, which tracks global energy markets, pushed the domestic diesel price to AED 4.30 per liter for September 2026, up 13% from AED 3.80 in August, the sharpest increase of any fuel category that month. That is a steep climb from AED 2.85 per liter back in December 2025.
For UAE businesses that depend on diesel for logistics, construction, agriculture, and power generation, this pricing mechanism means global supply shocks translate directly into monthly cost swings.
With the UAE also named among the exporters whose shipments have halved amid the regional disruptions, the country’s energy sector is watching this crisis from an unusually close vantage point.
What This Means for Fuel Buyers
The practical takeaway for anyone sourcing or supplying diesel right now is that price volatility is likely to stay elevated for several more months.
Locking in supply agreements, diversifying sourcing where possible, and building in cost buffers for logistics and fleet operations are sensible steps while refining capacity remains the binding constraint on global markets.
Fuel-intensive sectors, from farming to freight to fuel trading, are already adjusting.
In the U.S., some operators are cutting costs by consolidating deliveries and using smaller trucks to limit unnecessary trips, a sign of how deeply the price surge is reshaping day-to-day operations even outside the energy industry itself.